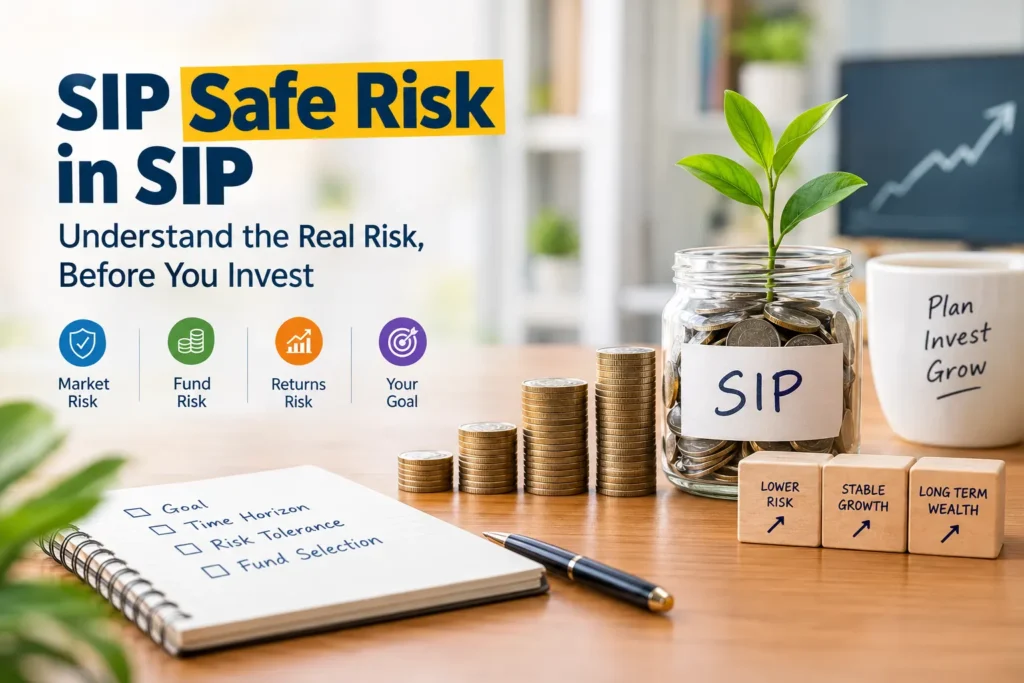
SIP safe risk in SIP depends on the mutual fund you choose, the market, your time frame, and your own ability to handle a fall. A SIP does not remove market risk. It only helps you invest at regular intervals. Your investment value can still fall.
SIP Risk Starts With the Fund
A SIP is a way to invest. It is not a fund type. The fund carries the main risk.
An equity fund can fall sharply. A debt fund can face credit and interest rate risk. A hybrid fund can carry risks from both equity and debt.
So, the first step is simple. Know what the fund owns.
Can SIP Go in Loss?
Yes. A SIP can show a loss.
Suppose you invest ₹5,000 every month. The market falls after you start. The value of your units may fall below the amount you have invested.
This can happen in the early years of a SIP. It does not always mean the plan has failed.
A SIP buys more units when prices are low. Later, a market rise can lift the value of those units. However, recovery is never guaranteed.
The fund must also remain suitable for your goal.
Can I Lose My Invested Money in SIP?
Yes, you can lose money.
The risk level depends on the assets held by the fund. Equity funds can face large market falls. Debt funds can face credit events. A concentrated portfolio can also suffer when a few large holdings fall.
There are other risks too.
A high expense ratio can reduce your net return. Exit load can reduce the amount you receive when you sell. Index funds can have tracking error. An active fund can face fund manager risk.
Style drift is another point to watch. A fund may slowly move away from the risk style you expected.
What Makes One SIP Less Risky?
There is no single SIP that is safe for everyone.
Your goal comes first.
Money needed in a short period needs careful risk control. Long-term money may have more room for market ups and downs.
Broadly diversified funds may reduce concentration risk. Still, they can fall when the wider market falls.
Debt funds may have lower market movement in some periods. Yet they can face credit risk and interest rate risk.
So, check the fund before you start the SIP.
Check These Points Before Starting
A fund should be checked from more than one angle.
First, check the portfolio.
See where the money is invested. Look for heavy exposure to one stock, sector, or issuer.
Next, check the cost.
Look at the expense ratio. Small costs can affect long-term results.
Then, check the exit load.
Know the cost of selling units within the stated period.
For index funds, check tracking error.
A large gap from the index can affect the result.
For debt funds, check credit quality and duration.
These can change the risk of the portfolio.
For active funds, check the fund manager and investment style.
A major change can affect how the fund behaves.
SIP Does Not Make a Bad Fund Good
A regular investment can be useful. It cannot repair a poor fund choice.
This point is often missed.
Some investors continue an old SIP for years without checking the fund. The fund may have changed. Its portfolio may have changed. Costs may have changed. The fund manager may have changed.
A SIP needs review when the reason for holding the fund changes.
The Real Disadvantages of SIP
SIP has clear limits.
It does not guarantee a return. It does not protect your capital. It does not stop a market fall.
There can also be missed instalments when cash flow is tight. Exit loads may apply. Taxes can affect the final amount.
Inflation is another concern. Your money may grow in value while its buying power grows more slowly.
A long SIP can also hide a weak fund if you never review it.
Is SIP 100% Safe in India?
No investment linked to the market is 100% safe.
Mutual funds in India operate under a regulated framework. That does not mean every scheme gives a fixed return.
The fund still carries market risk. The portfolio still carries asset risk. Your final value can rise or fall.
Fraud risk also needs attention.
Never share an OTP or password. Do not send investment money to an unknown personal account. Check the fund name, platform, and payment details before you invest.
How to Judge Mutual Fund SIP Returns
Mutual fund SIP returns should be viewed over a suitable period.
A three-month result can change very fast. A longer period gives more useful information.
Look at the return along with the risk taken. Check past falls. Check drawdowns. Check the portfolio. Check the cost.
A high return with a very large fall may be hard for many investors to hold.
The best fund on paper can still be a poor fit if you cannot stay invested during a bad market.
FD or Mutual Fund: What Fits the Goal?
An FD gives a known rate for its chosen term, subject to its terms.
A mutual fund gives market-linked returns. Its value can rise or fall.
The choice should follow the goal.
Money needed on a fixed date may need lower volatility. Long-term goals may allow more market-linked assets.
Tax, liquidity, inflation, and risk capacity also matter.
There is no universal winner. The product should fit the job the money needs to do.
A Practical SIP Decision
Before starting a SIP, write down four things:
- Your financial goal
- Your investment time
- Your monthly amount
- The fall you can tolerate
Then check whether the fund fits those limits.
Review it when the portfolio, cost, mandate, or risk changes.
Do not stop a suitable long-term SIP because of one weak month. Also, do not keep a weak fund simply because you have invested in it for years.
A sound SIP decision comes from knowing what you own, why you own it, and how much risk you can carry.
FAQs – is sip safe risk in sip
Is SIP mutual fund risky?
Yes. SIP carries the risk of the mutual fund scheme. Equity funds can fall sharply. Debt funds can face credit and interest rate risk.
Can I lose my invested money in SIP?
Yes. The value of your investment can fall below the amount you have invested. The loss depends on the fund, market, and time of sale.
Is SIP 100% safe?
No. SIP is an investment method. It does not guarantee your money or your return.
Is SIP better than FD?
Both serve different needs. An FD gives a known rate for its term. A mutual fund has market-linked returns. The choice depends on your goal, time, liquidity, tax, and risk level.
Which SIP is less risky?
There is no SIP that is risk-free. Lower-risk options can still face credit, interest rate, or market risk. Always check the scheme and its portfolio.
What are the disadvantages of SIP?
SIP does not guarantee returns. Your investment can fall. Costs, exit loads, taxes, missed instalments, inflation, and poor fund selection can also affect your result.